“Everyone has a plan until they get punched in the mouth.” — Mike Tyson
The municipal bond market got punched in the mouth this week with municipal bond yields rising across the board at a much higher level than treasuries. Below we have a chart showing last week's rise in Treasury yields and last week's rise in municipal bond yields and the change in the yield ratios of the Muni to Treasury market.
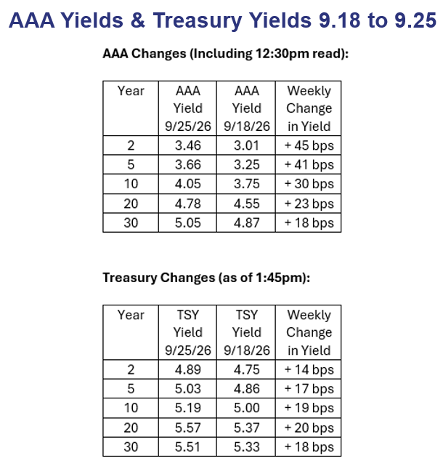
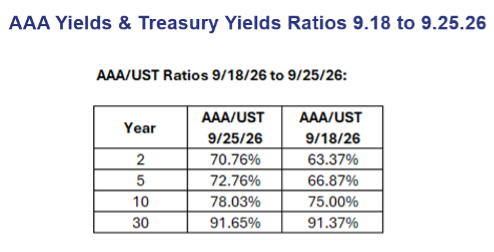
You can see that the yield ratios increase or are most pronounced in the shorter end, but even in the longer end, the jump in ratios is much larger than a normal week. What caused this?
Number 1, municipal bond yields tend to lag treasury yields on the way up and on the way down. The reason for this is that you do not need to have the same amount of yield change that you have in treasuries to have an equivalent amount of taxable equivalent yield change. However, with municipal bond yields following treasuries on a very sluggish path as treasury yields went higher, they leaped forward this week in catching up because of some unfriendly bond news in the Treasury market.
Number 2, we saw a jump in oil prices this past week because of the ongoing conflict with Iran.
Number 3, we saw a large jump in the PMI purchasing managers’ index to 58, much higher than expected. That increased investors' thoughts that the economy was expanding at a faster rate and that would require more Federal Reserve rate hikes on top of the quarter-point increase in the Fed funds rate from the meeting two weeks ago.
Number 4, a large amount of municipal bond supply towards the end of September, and it was at a period where municipal reinvestment funds tend to be on the low side.
Number 5, some bad headline news in the bond market with the bankruptcy of the Bright Line Railroad in Florida. Though that was a high yield bond project, it did have ripple effects through the Muni market for credit concerns in general.
We feel the municipal bond yields are extremely attractive now after this latest sell-off. And we believe that you will start to see crossover buyers come into the market. Those are non-traditional municipal bond investors who usually invest in taxable bond instruments. These would include things like taxable bond investors such as life insurance companies. We believe at these levels tax-free bond yields offer some compelling returns, and particularly compelling returns when we look at their yields versus inflation.
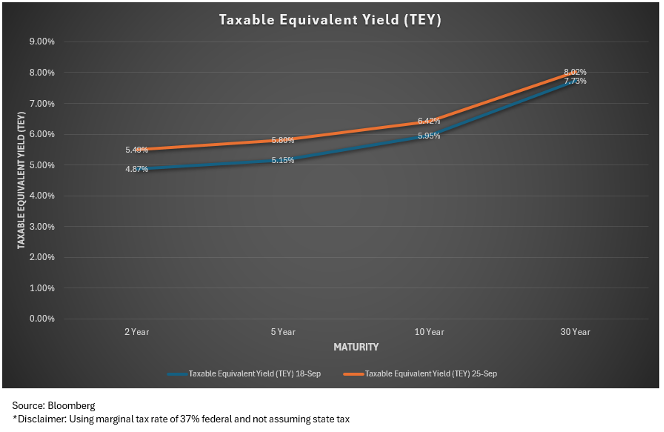
The last chart shows the municipal bond yield curve as of the end of last week, on a taxable equivalent basis.